How Much Is Home Insurance? A Breakdown of What You Actually Pay
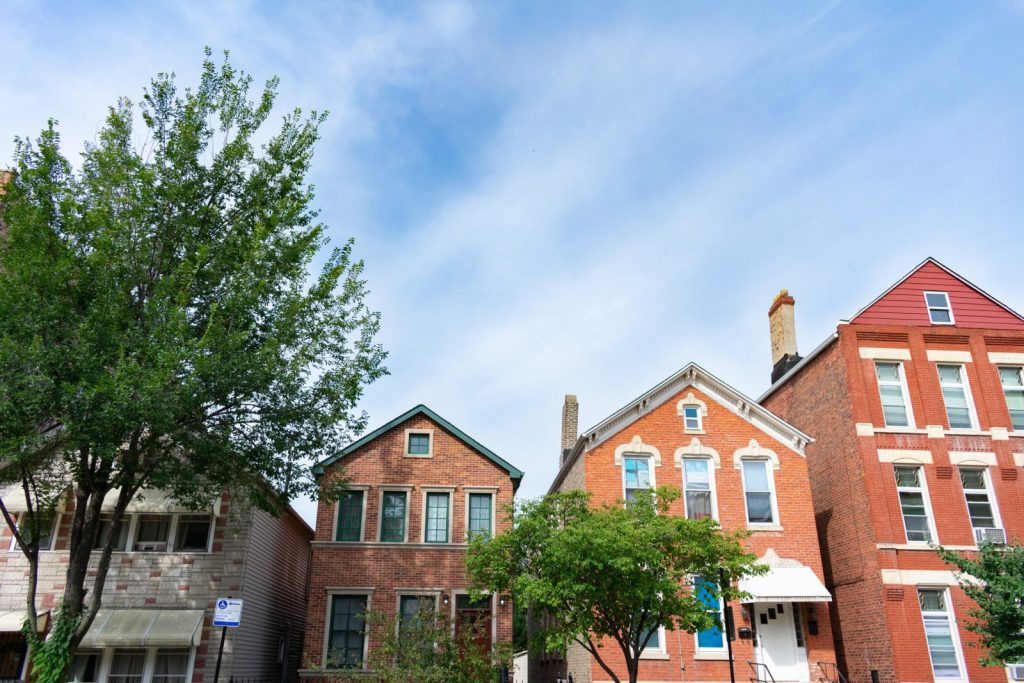
According to a 2026 report, Illinois homeowners pay an average of $2,731 a year for homeowners insurance, 14 percent above the national average. That number is a useful starting point, but it is an average, not a guarantee of what you will end up paying.
Whether you’re buying your first home or it’s time to reassess your current coverage, understanding what goes into that price helps you budget accurately and feel more confident at closing or renewal.
Everything That Determines The Cost of Home Insurance
Homeowners insurance costs vary by property, and they also depend on whether you’re a new homeowner or looking to renew coverage. The basic costs that both new and existing homeowners would have to consider include replacement costs, home age, construction materials, and location. Aside from those things, what you should pay heavily depends on the stage of homeownership you’re in.
For New Homeowners
If you are buying for the first time, home insurance is a new expense to budget for, not an adjustment to an existing one.
Your focus should be on:
- Getting an accurate replacement cost estimate rather than insuring your home based on the purchase price
- Choosing coverage limits and a deductible that fit your budget and risk tolerance
- Asking about discounts upfront, such as bundling with other policies
- Building the premium into your overall closing and monthly payment estimate
For Current Homeowners
If you already own your home, cost is more often shaped by what changed since your last policy review.
That looks like:
- Claims history and credit-based insurance score, both of which can shift your premium during renewal
- Replacement cost updates after renovations, additions, or rising construction costs, since outdated coverage can leave gaps
- Discounts you may be missing, such as a newer roof or upgraded security system that was never reported to your carrier
- Comparing your current premium against the state average periodically, rather than assuming it is still competitive
Understanding what goes into the cost of home insurance isn’t just about protecting your home. It’s also important because of its impact on your monthly mortgage payments.
How Home Insurance Affects Your Mortgage Payment
Most lenders require homeowners insurance and collect the annual premium through an escrow account, merging it into your monthly mortgage payment along with principal, interest, and taxes. A higher premium raises your total monthly payment even if your loan terms stay the same. Because of this, shopping for competitive home insurance costs is not just about protecting your property. It is part of managing your overall housing budget. If you are exploring mortgage options in Chicago, it helps to factor insurance into your monthly payment estimate from the start.
Getting a Quote Helps You Figure Out How Much Coverage You Need
The state average tells you what Illinois homeowners pay on average; whereas a quote is a personalized estimate that tells you what your home will cost to protect. That home insurance quote is created based on your property details, including square footage, age, roofing materials, and recent updates, giving you an accurate cost. Coverage should also account for the structure itself, other buildings like garages or fences, personal belongings, and personal liability.
To get the customized coverage you need, talk to a local insurance advisor to get a coverage estimate built around your property.
Disclaimer
This article is for educational purposes only and does not constitute financial, legal, or tax advice. For personalized guidance, please consult with a qualified professional.
Liberty Insurance Agency, Inc. acts solely as an insurance agent and does not make any claims determinations. All claims are subject to review and decision by the respective insurance carrier in accordance with the terms and conditions of the policy.
Quotes are subject to current comprehensive loss underwriting exchange report (CLUE), credit, property inspection, company underwriter approval, and motor vehicle report (MVR). Most quotes are valid for 30 days.
Liberty Insurance Agency, Inc., is a subsidiary of Liberty Bank for Savings. Insurance products and services are not bank products or services and are not FDIC insured or insured by any federal government agency. They are not a deposit or obligation of, or guaranteed by, Liberty Bank for Savings and may involve investment risk, including possible loss of principal. Applicants are individually underwritten and some individuals may not qualify.